Florida Insurance Appraiser for underpaid property claims
Your insurer says $18,000. Your roofer says $41,000. Florida Insurance Appraiser closes that gap with measurements, photos and a line-by-line estimate the other side has to answer — for homeowners, condo associations and commercial owners from Pensacola to Key West.
- Xactimate & Symbility estimates
- Residential & commercial
- Umpire services
Why the insurer’s number and your contractor’s number never match
Most underpaid Florida claims aren’t the result of one big disagreement. They’re dozens of small ones: a roof measured without its waste factor, a tile line item swapped for shingles, drywall priced for one wall instead of the whole room, matching ignored, code upgrades left off and contractor overhead and profit quietly removed.
A Florida Insurance Appraiser finds those differences one line at a time and puts a documented price on each of them. That is what an appraisal panel weighs — not who argues loudest, but whose estimate holds up item by item.
Illustrative example: a hip-roof hurricane claim
| Line item | Carrier | Re-estimate |
|---|---|---|
| Roof area (squares) | 28.0 | 33.6 |
| Waste factor | 0% | 15% |
| Drip edge & starter | Omitted | Included |
| Code-required underlayment | Omitted | Included |
| Interior ceiling repairs | 1 room | 3 rooms |
Hypothetical figures to show how small line items add up. Every claim is different.
What Florida Insurance Appraiser handles
From a single water-damaged kitchen to a 200-unit condominium tower, every assignment starts the same way: an honest read of the policy, the insurer’s estimate and the gap between them.
Homeowners Claim Appraisal
Independent appraisal for Florida homeowners whose insurer agrees the loss is covered but disagrees on what it will cost to repair.
Learn more →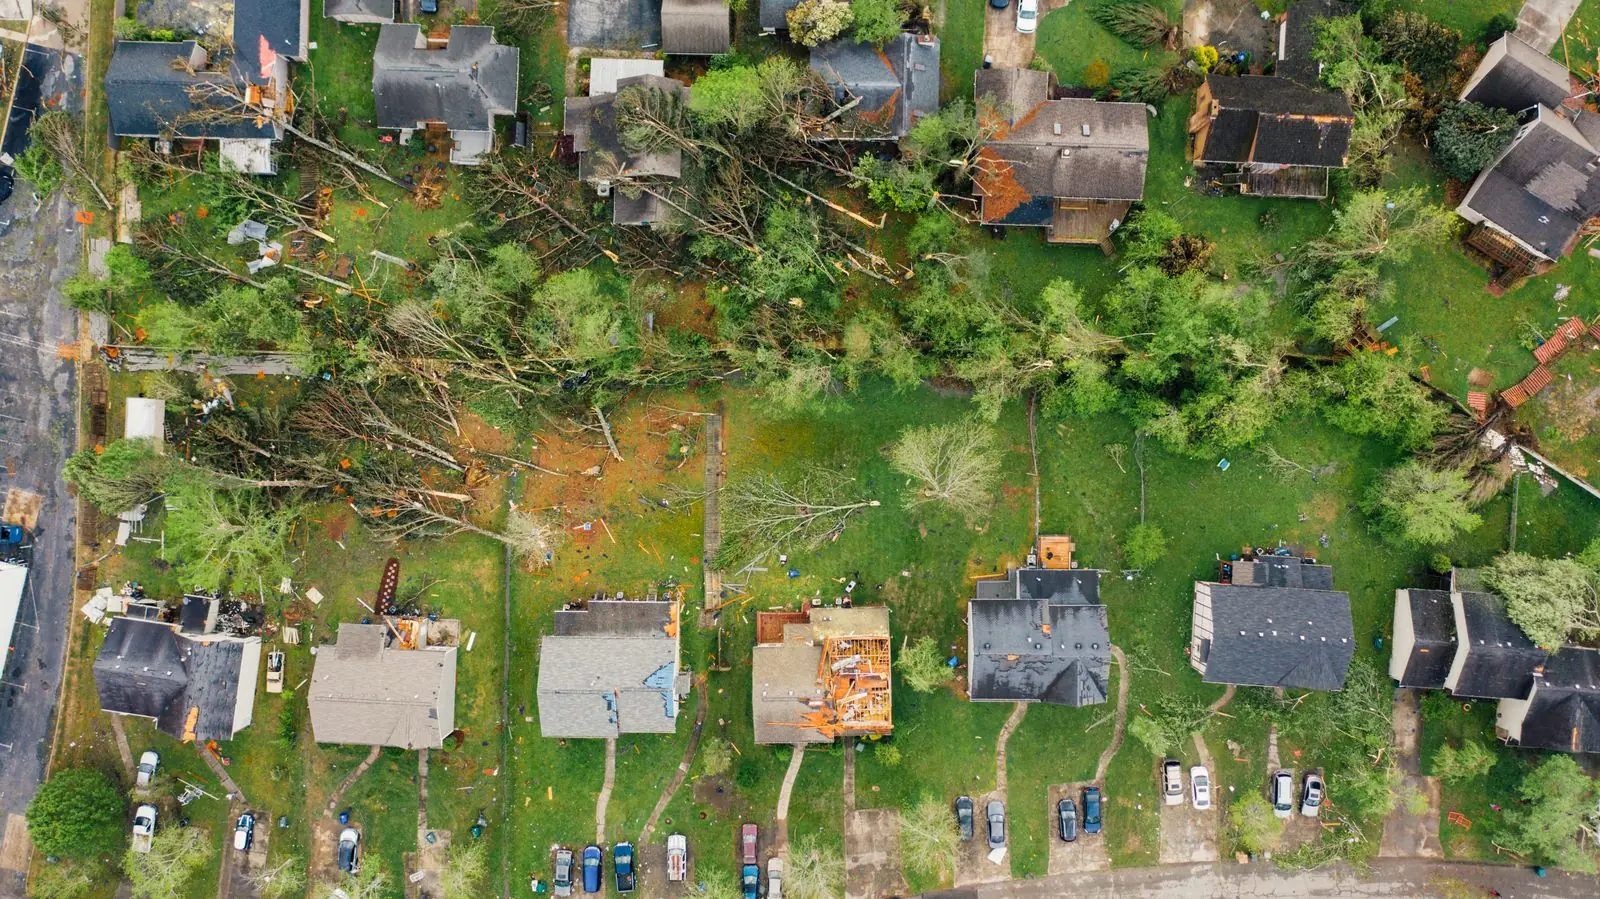
Hurricane Claim Appraisal
Appraisal for windstorm and hurricane losses across Florida, from roof and soffit damage to wind-driven rain and interior repairs.
Learn more →
Roof Claim Appraisal
Roof-focused appraisal for shingle, tile, metal and flat roofs, covering measurements, matching, code items and roof payment schedules.
Learn more →
Water Damage Claim Appraisal
Appraisal for sudden plumbing, appliance and roof-leak water losses, covering mitigation, tear-out, drying and rebuild costs in Florida homes.
Learn more →
Sinkhole Claim Appraisal
Appraisal for accepted Florida sinkhole and ground-collapse claims, focused on repair scope, stabilization costs and above-ground damage.
Learn more →
Fire & Smoke Claim Appraisal
Appraisal for fire, smoke and soot losses, covering structural rebuild, cleaning versus replacement, contents and additional living expenses.
Learn more →How appraisal works with a Florida Insurance Appraiser in your corner
Policy & estimate review
We read the appraisal provision, deductibles and endorsements, then compare the insurer’s estimate with yours.
Written demand
If the gap justifies it, appraisal is invoked in writing and each side names a disinterested appraiser.
Inspection & negotiation
We inspect, measure and document, then work through the estimates with the insurer’s appraiser line by line.
Umpire & award
Items still in dispute go to a neutral umpire. An award signed by two of the three sets the amount of loss.
Built for the claims Florida actually gets
Hurricane season runs June 1 through November 30, but Florida losses don’t keep a calendar: summer thunderstorms, plumbing failures, kitchen fires and ground movement fill the other months. After a named storm, insurers face thousands of claims at once, and desk-adjusted estimates written from photos become the norm. That is when a Florida Insurance Appraiser earns their fee.
We know the difference between wind and surge, how percentage hurricane deductibles change the math, and why a 2001 tile roof in Broward is priced nothing like a 2019 shingle roof in Ocala. Hurricane claim appraisal →
Free claim tools from Florida Insurance Appraiser
Run the numbers yourself before you call anyone. No sign-up, nothing stored on our servers.
Appraisal Worth-It Calculator
Compare the disputed amount against what appraisal is likely to cost you, across low, middle and full-recovery scenarios.
Open tool →Hurricane Deductible Calculator
Turn a 2%, 5% or 10% hurricane deductible into dollars, track what you’ve already absorbed this year, and estimate your payout.
Open tool →ACV & Depreciation Calculator
Estimate depreciation and actual cash value for roofs, flooring, HVAC and contents using age and expected service life.
Open tool →Claim Deadline Calculator
Plug in your date of loss to map Florida’s key claim-notice windows and the insurer’s typical response timelines.
Open tool →Roof Measurement Calculator
Convert a home’s footprint and pitch into roof squares, waste, shingle bundles and underlayment — then compare against the insurer’s estimate.
Open tool →Contents Inventory Builder
Build a room-by-room list of damaged belongings with replacement cost and estimated ACV. Saves in your browser and exports to CSV.
Open tool →Appraisal vs. the other ways to resolve a Florida claim dispute
Appraisal isn’t the right tool for every problem. Here’s how it compares, in plain terms.
| Option | Best for | Decides | Typical pace |
|---|---|---|---|
| Appraisal | Covered losses where the dispute is the dollar amount | Amount of loss only | Weeks to a few months |
| DFS mediation | Residential disputes where both sides may settle with a neutral’s help | Nothing unless both sides agree | Often a single session |
| Public adjuster | Owners who want the whole claim prepared and negotiated for them | Negotiated settlement | Varies with the claim |
| Litigation | Coverage denials, bad faith and legal questions | Coverage and damages | Often a year or more |
General comparison, not legal advice. A Florida Insurance Appraiser decides amount-of-loss questions only; coverage questions belong with an attorney.
A Florida Insurance Appraiser for every coast
We work claims statewide — the high-rise condos of Miami-Dade and Broward, the older block homes of Tampa Bay, the barrier islands of Lee and Collier, the oak-canopy neighborhoods of Tallahassee and the Panhandle beaches still rebuilding from recent storms.
Homeowners
Single-family homes, townhomes and condo unit owners with HO-3, HO-6 or dwelling policies.
Condo associations
Master-policy claims, shared elements and building-wide water or wind losses.
Commercial owners
Retail, office, warehouse, hospitality, churches and multifamily properties.
Contractors & counsel
Estimate support and appraisal for roofers, restoration firms and attorneys’ clients.
Questions people ask a Florida Insurance Appraiser
Short answers to what we hear most. More in the full FAQ and the claim glossary.
What does a Florida insurance appraiser actually do?
When you and your insurance company agree a loss is covered but disagree on how much it costs to repair, the appraisal provision in most Florida policies lets each side appoint an appraiser. As your Florida Insurance Appraiser, we inspect the property, build or review a line-item estimate, and negotiate the amount of loss with the insurer’s appraiser. If we can’t agree, a neutral umpire decides the disputed items.
Is appraisal binding in Florida?
An appraisal award signed by any two of the three participants (the two appraisers and the umpire) generally sets the amount of loss under the policy. It does not decide coverage questions, and your policy’s exact wording controls.
How is appraisal different from hiring a public adjuster or attorney?
A public adjuster manages and negotiates the whole claim, and an attorney handles legal disputes such as denials and bad-faith issues. Appraisal is narrower and usually faster: it focuses only on the dollar amount of a covered loss. See our side-by-side comparison.
Can I invoke appraisal after the insurer has already paid something?
Often, yes. Many owners invoke appraisal after an initial payment that doesn’t cover the actual repair cost. The award is reduced by prior payments and your deductible. Check your policy’s timing requirements first.
Do you handle condominium and commercial claims?
Yes. Florida Insurance Appraiser works with condo associations on master-policy claims and with owners of retail, office, warehouse, hospitality and multifamily properties, where scope and code-upgrade questions tend to be larger.
What does it cost to talk to you?
The first conversation and a look at your insurer’s estimate cost nothing. If appraisal makes sense, we explain our fee in writing before anything is signed.
Guides for Florida policyholders
Florida Roof Claims After the 2022 Insurance Reforms
Roof payment schedules, the updated 25% rule, shorter claim windows and AOB changes: what Florida’s 2022 reforms mean for a roof claim today.
Read · 9 min →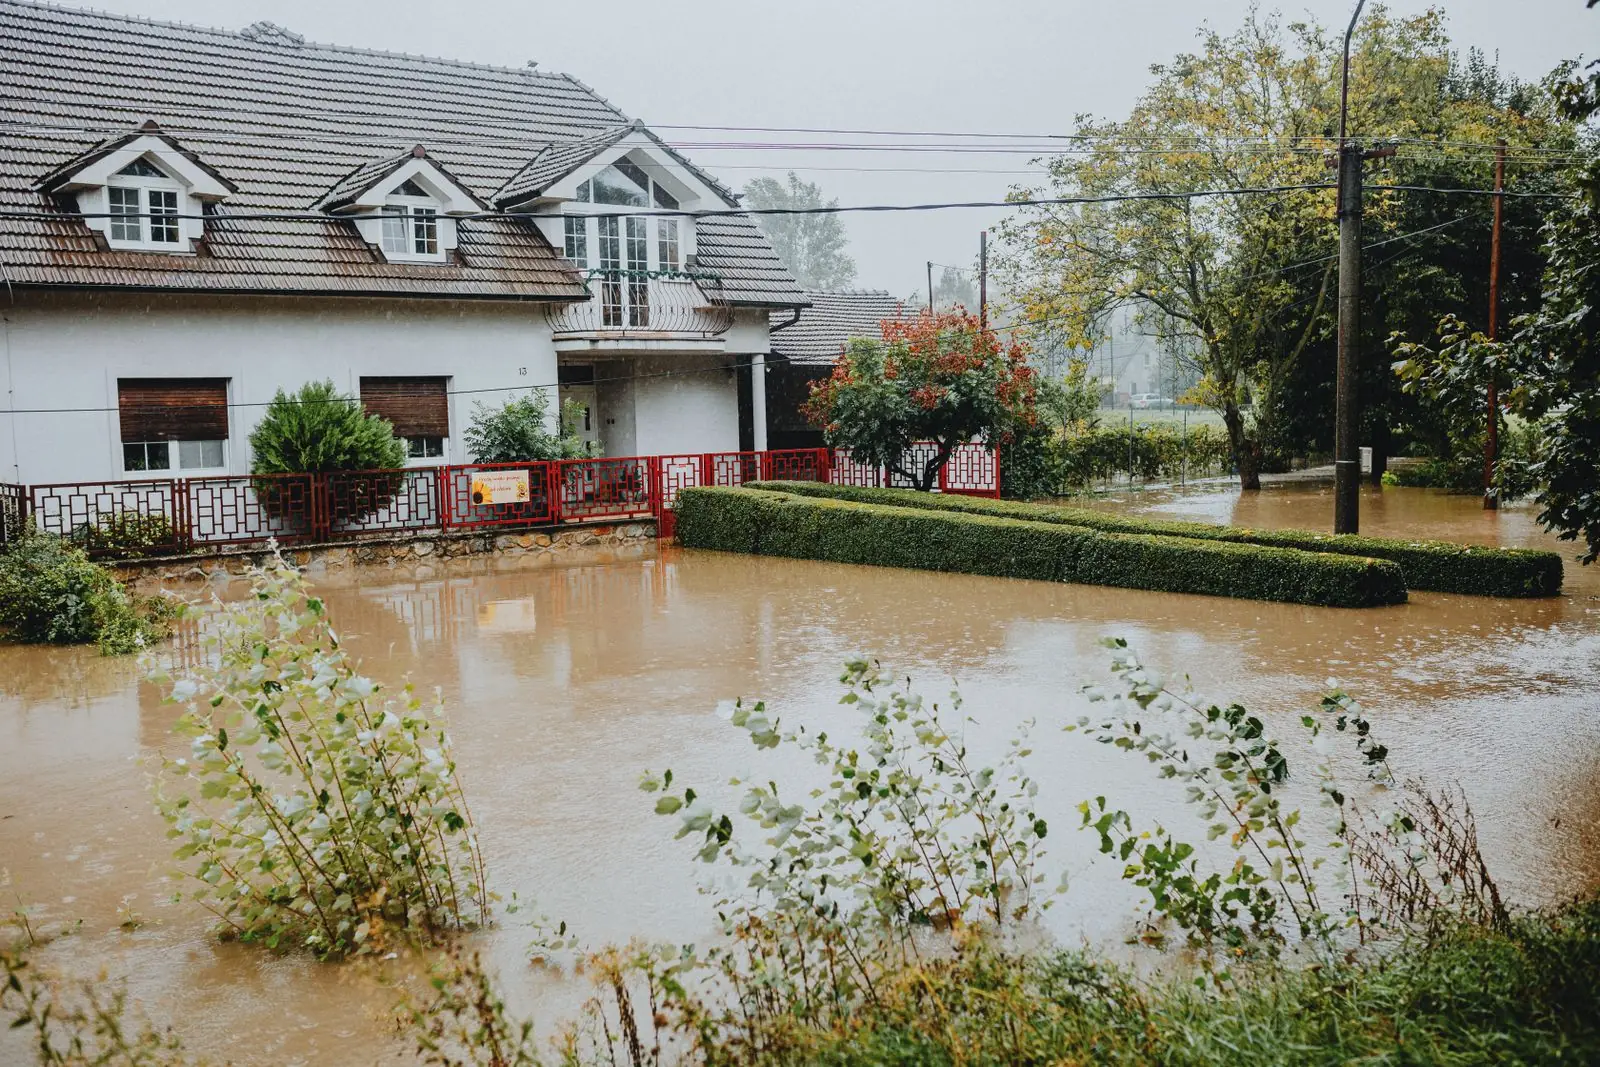
What to Do When Your Florida Property Claim Is Underpaid
A step-by-step plan for a Florida claim payment that will not cover repairs: decode the estimate, document, request review, mediate or appraise.
Read · 8 min →
Appraiser, Public Adjuster or Attorney? Choosing Help for a Florida Claim
An honest comparison of appraisers, public adjusters and property insurance attorneys in Florida, and how to tell which one your claim actually needs.
Read · 8 min →Talk to a Florida Insurance Appraiser about your claim
Tell us what happened and where the claim stands. We’ll look at the numbers and tell you honestly whether appraisal, a supplement, mediation or something else makes the most sense — even if the answer is that you don’t need us.
- +1 (844) 537-1427
- info@floridainsuranceappraiser.com
- Statewide — all 67 Florida counties
Florida Insurance Appraiser provides appraisal and estimating services. We are not a law firm and do not give legal advice.